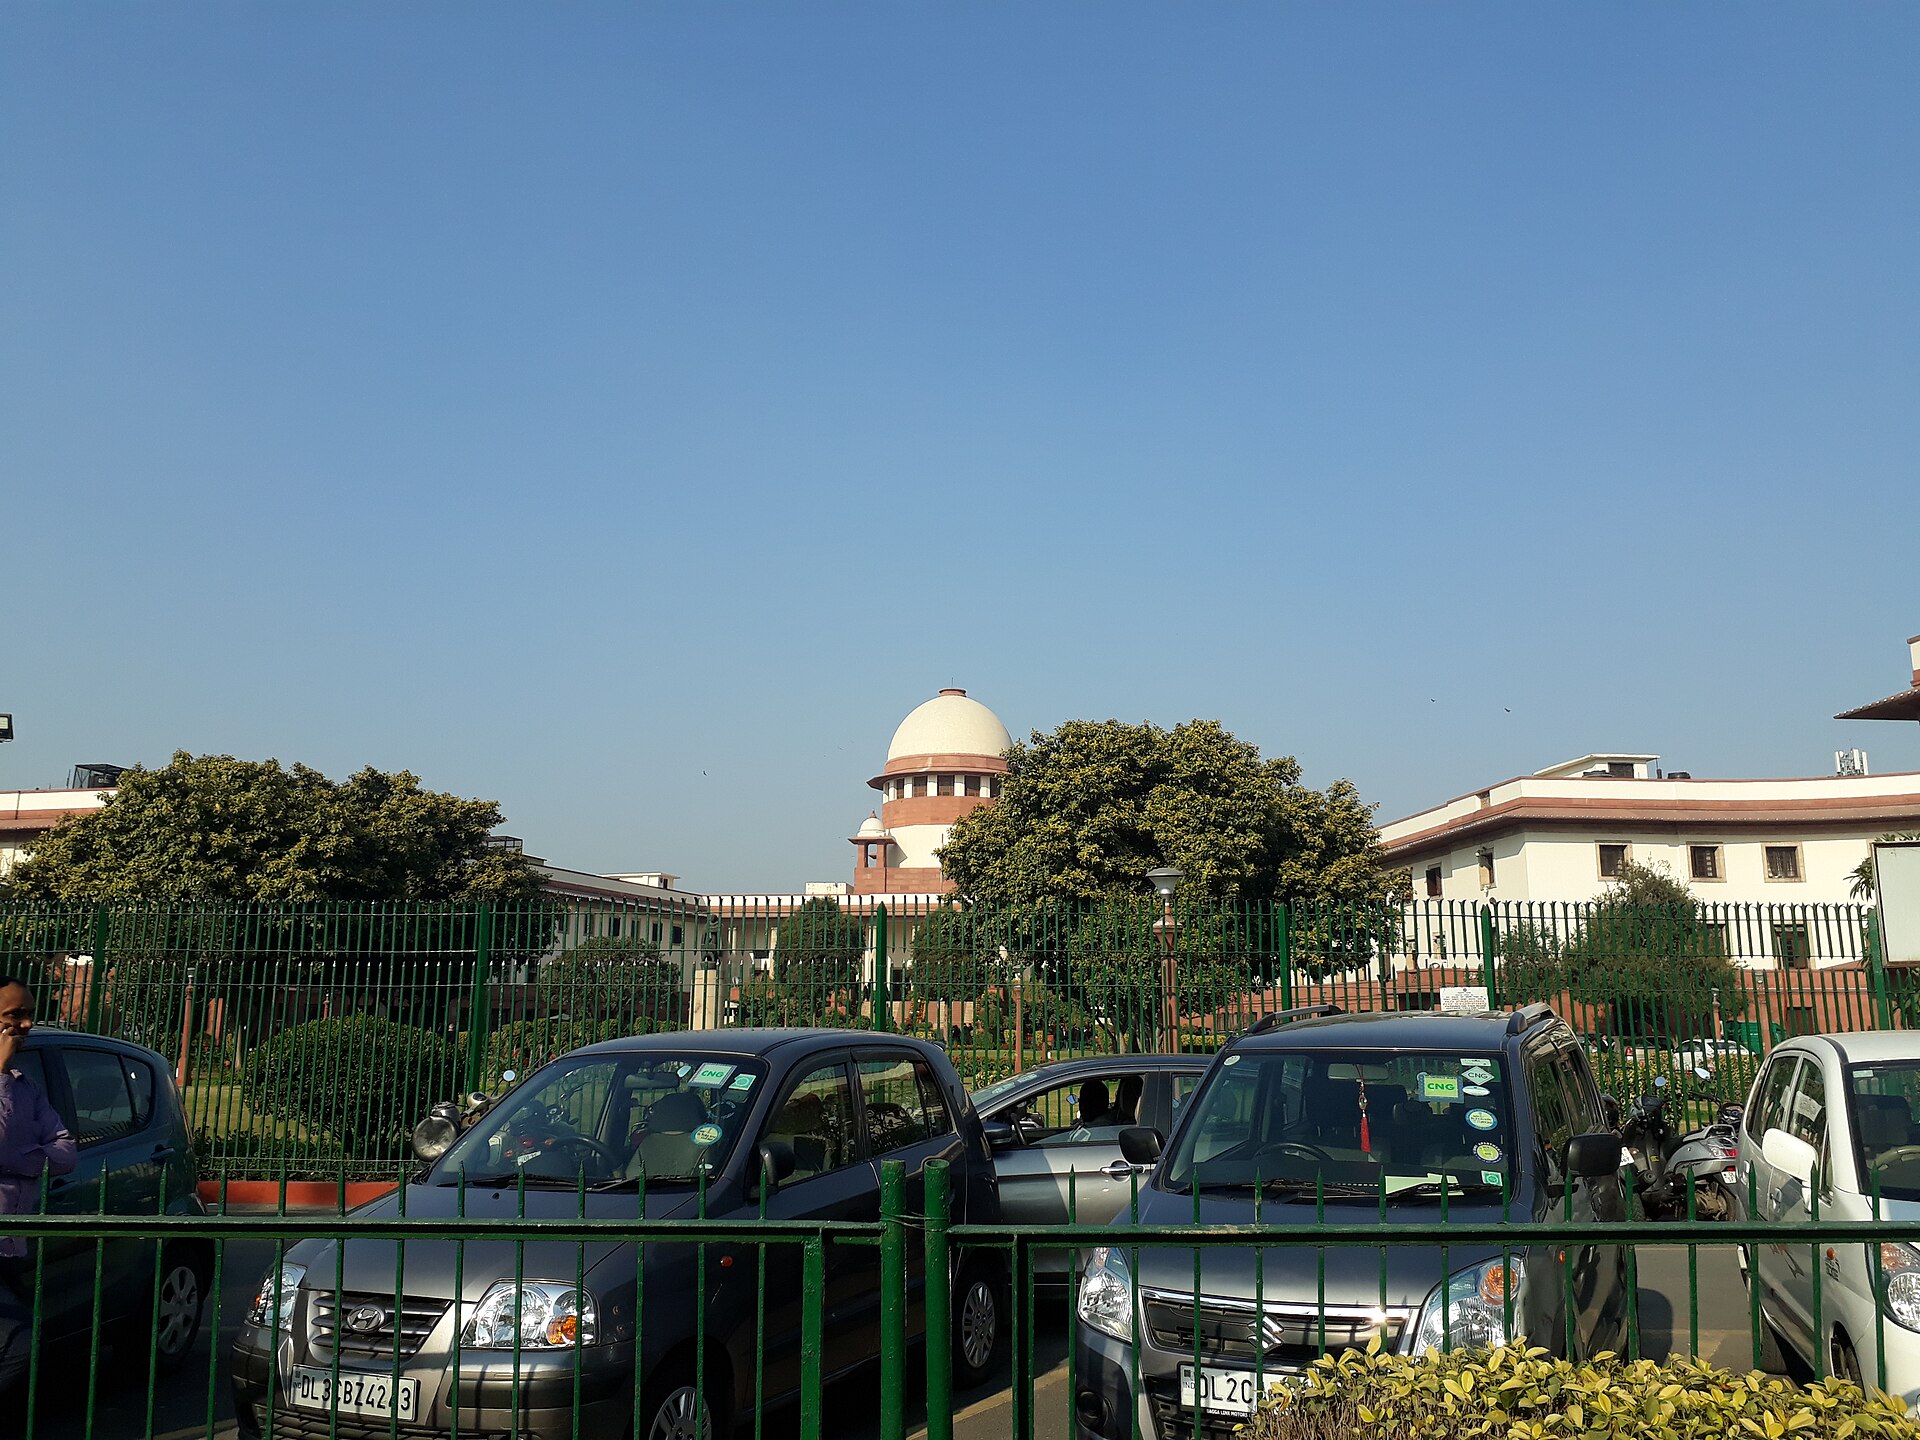
The Supreme Court said on Thursday, October 29, that the Reserve Bank of India’s proposed Know Your Customer (KYC) Amendment Directions, 2026 must require banks and other financial institutions to compensate victims of digital arrest and cyber fraud. The payout should be no less than the amount lost wherever an investigation finds that the fraud resulted from the institution’s failure of due diligence.
A bench of Chief Justice Surya Kant and Justices Joymalya Bagchi and V Mohana said it would examine the draft before it is notified. Attorney-General R Venkataramani told the court the directions would be notified by November 30 and take effect by December 31. The bench also wants preventive steps in the rules: temporary suspension of transactions that depart from an account’s usual pattern, automated alerts to the nearest police station, and physical verification where needed. It asked the RBI for a list of all authorised financial institutions, so that its directions apply across the sector without each bank joining the case.
The court noted that victims have lost about ₹800 crore so far this year, even though cyber crimes have fallen by 50%. The Attorney-General said the RBI is examining the liability of banks and of individual officials, including prosecution where staff collude in a fraud. The case returns before November 30.
Why it matters: Victims of digital arrest scams usually bear the loss today, and a liability clause would move part of that cost to the bank that let the money leave. Banks would then have a direct financial reason to spend more on transaction monitoring and to hold payments that look unusual, which may also mean more delayed transfers for genuine customers. The detail to watch is who decides that due diligence failed, and how quickly a victim gets paid.
Source: The Hindu; Verdictum; The Hindu BusinessLine
Image: Pinakpani, CC BY-SA 4.0, via Wikimedia Commons